How to Set Up Your Finances When You First Arrive in Hong Kong
Open the right bank account, set up Octopus and FPS, and avoid costly transfer fees. A practical money setup guide for new arrivals in Hong Kong.
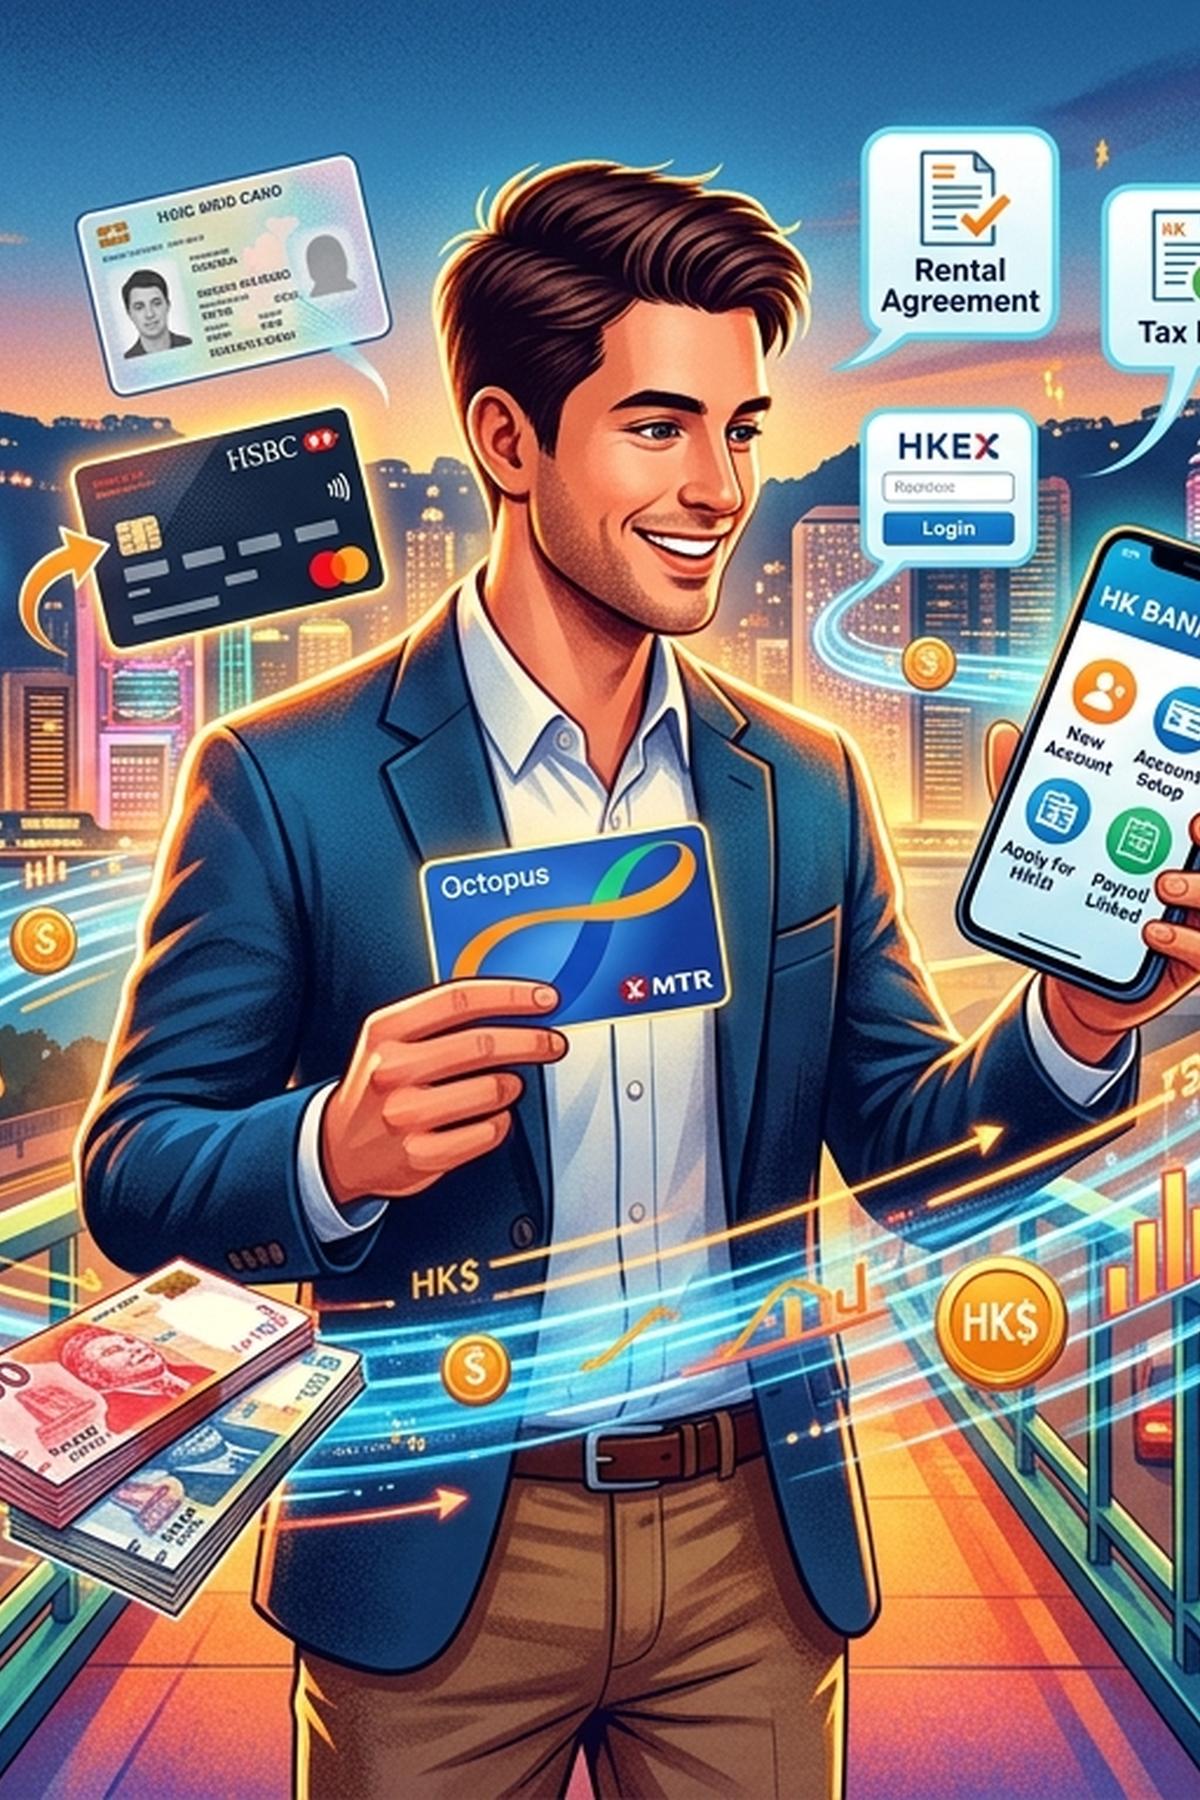
Your boxes are barely unpacked and your new employer is already asking for bank account details you do not yet have. Hong Kong's financial system is efficient and modern, but it assumes you already know how it works. Most new arrivals spend their first two weeks paying for everything in cash, missing payroll deadlines, and quietly paying far too much every time they send money back home. None of that needs to happen to you.
Get these three priorities sorted in your first fortnight and you sidestep the financial pitfalls that catch almost every new arrival off guard.
- Open a bank account at a foreigner-tolerant institution before your employer processes your first paycheck
- Set up an Octopus card and register for the Faster Payment System so you can pay, receive, and split costs from day one
- Lock in a low-fee overseas transfer route before that first salary lands, not after
Getting Your Bearings with Hong Kong Dollars First
HKD is pegged to the US dollar at a band of roughly 7.75 to 7.85. Bills circulate in denominations of 20, 50, 100, 500, and 1,000 HKD. Coins cover 10 cents up to 10 dollars. Three commercial banks issue their own note designs alongside government-issued coins, which can confuse newcomers, but all denominations are legal tender regardless of which bank printed them.
Card acceptance varies more than most expats expect. Visa and Mastercard work reliably at supermarkets, chain restaurants, and most large retailers. Small shops, wet markets, dai pai dong (open-air food stalls), minibuses, and many traditional businesses still expect cash or Octopus. American Express has noticeably patchier coverage and is not worth relying on for daily spending.
Before you open any accounts, take a few minutes with a solid Hong Kong money guide to get comfortable with denominations, ATM conventions, and what to expect at different types of businesses. That grounding makes the account-opening process much less disorienting once you are standing at a bank counter with a stack of documents and a jet-lagged brain.
Which Banks Actually Want Your Business as a New Arrival
Not all Hong Kong banks are equally welcoming to freshly arrived expats, particularly if you have limited local documentation and no address history in the city.
HSBC Hong Kong is the most widely used option for incoming expats. Their account tiers are familiar to most foreign nationals, English-language service is consistent, and HR departments across the city are comfortable processing payroll into HSBC accounts. The catch is a minimum combined balance of HKD 5,000 across your accounts to avoid a monthly service fee. Falling below it regularly costs you, so keep an eye on it in your first few weeks when cash flow is unpredictable.
Standard Chartered HK is a strong alternative. Their Bonus$aver account ties interest rate tiers to how actively you use the account, which rewards the kind of consolidated banking most salaried expats end up doing anyway.
Hang Seng Bank is majority-owned by HSBC and offers a comparable product suite. It is worth considering simply because branches tend to be less crowded and service can move faster than at a flagship HSBC location.
Bank of China (HK) works well if you regularly transfer money to or from mainland China. The onboarding process can be more involved than at HSBC or Standard Chartered, and staff English varies by branch, so factor that into your expectations.
ZA Bank and Mox Bank are Hong Kong's licensed virtual banks, and they deserve serious consideration. ZA Bank in particular has become popular with newly arrived expats. There is no minimum balance, no monthly fee, and the account can be opened entirely through the app in under 10 minutes using just your passport and proof of address. The one area to verify is whether your company's payroll team recognises virtual bank account numbers. This has become much less of an issue over the past few years, but a confirmation with HR before you commit is worth the 30 seconds it takes.
What Documents You Will Need to Open an Account
- Your passport (original, not a photocopy)
- A valid Hong Kong visa or entry stamp
- Proof of address (tenancy agreement, utility bill, or a recent bank statement from your home country)
- Proof of employment (offer letter or employment contract on company letterhead)
If you have just arrived and have not yet signed a lease, ask your employer for an official letter confirming your position and local work address. Many banks accept this in place of a utility bill, but you may need to specifically request this option at the counter. Do not assume the teller will volunteer it.
Choosing the Right Account Type for Your Salary
How Key Hong Kong Banks Stack Up for Newly Arrived Expats
| Bank | App-Only? | Approx. Min. Balance | Best For |
|---|---|---|---|
| HSBC HK | No | HKD 5,000 combined | Payroll, broad branch access, broad expat familiarity |
| Standard Chartered HK | No | Varies by account tier | Interest rewards on actively used accounts |
| Hang Seng | No | Varies by account tier | Less crowded branches, HSBC-equivalent service |
| ZA Bank | Yes | None | Fast setup, no fees, ideal for new arrivals |
| Mox Bank | Yes | None | Multi-currency features, Cathay miles integration |
Most companies in Hong Kong process payroll via CHATS (the Clearing House Automated Transfer System) or FPS, both of which work across any licensed local bank. You are not locked into using the same institution as your employer. Confirm this with your HR team if they suggest a specific bank. Payroll cutoff dates are real, though. Miss the submission window for your banking details and you may wait a full calendar month for your first paycheck.
Multi-currency accounts are worth serious thought if your financial life spans more than one currency. HSBC's Everyday Global Account and Citibank's Global Account both hold multiple currencies at once. If your salary arrives in USD or GBP, or if you carry regular expenses in more than one currency, these eliminate a lot of daily conversion friction.
Octopus and FPS: Two Systems That Quietly Power Daily Life
Octopus is a stored-value contactless card that has been running Hong Kong's transit network since 1997. It works on the MTR, every bus route, minibuses, trams, ferries, the Airport Express, and at thousands of retail locations including 7-Eleven, McDonald's, ParknShop, and Wellcome. You do not need a bank account to get one. Walk into any MTR customer service centre and buy one for a HKD 50 refundable deposit plus whatever top-up you want to start with. Register the card online or via the Octopus app to protect your balance if the card is ever lost or damaged.
FPS is the Faster Payment System. It lets you send and receive money between any Hong Kong bank account or stored-value service using just a mobile phone number or HKID number as the identifier. No account numbers. No routing codes. Under the payment settlement rules published by the monetary authority that oversees the system, FPS transfers settle in real time, around the clock, including weekends and public holidays.
Once your bank account is open, register your Hong Kong mobile number for FPS through your bank's app. The process takes about two minutes. From that point forward, anyone who wants to pay you, split a bill with you, or reimburse you for anything will simply ask for your phone number. FPS has effectively replaced the clunky process of exchanging account numbers for personal transfers in this city.
Sending Money Overseas Without Paying Bank Exchange Rates
Hong Kong banks offer international wire transfers, but their exchange rates typically sit 2 to 4 percent below the real mid-market rate. On a monthly transfer of HKD 30,000 (roughly GBP 3,000 or around USD 3,800), that gap compounds into a meaningful loss over the course of a year.
Wise and Instarem are the two most established low-fee transfer services used by Hong Kong-based expats. Both charge transparent fees and use mid-market exchange rates. Wise performs consistently for transfers to the UK, Europe, Australia, and the US. Instarem has historically had an edge for transfers to Southeast Asia and the Indian subcontinent.
Register for whichever service fits your destination country before your first salary arrives. Verification can take a day or two if your documents require manual review, and you want that account ready to use immediately. Transfers from Hong Kong using Wise require you to fund the transfer from a local bank account, so you cannot bypass the local banking step entirely. You just bypass the bank's exchange rate, which is the part that matters.
What to Sort Before That First Paycheck Lands
Submit your bank account details to HR as early as possible. Payroll in Hong Kong typically runs monthly, paid on the last few days of the month or the first few days of the following one. Most companies have a hard cutoff for banking information, and a late submission can delay your first pay by an entire month.
If your account is not ready in time, ask HR whether they can issue a one-off cheque as an interim measure. Most companies will accommodate this for new starters, but you need to ask early rather than raising it on payday.
Account for MPF deductions from the start. The Mandatory Provident Fund requires both you and your employer to contribute 5 percent of your relevant monthly income, up to a statutory cap, once you have been employed for 60 days. That deduction appears on your payslip and reduces your net take-home amount from the first eligible pay cycle. Build it into your budget before you arrive rather than being surprised by it in month two.
Your Financial Foundation in Hong Kong Is Built in the First Two Weeks
The financial admin of arriving in Hong Kong is genuinely manageable once you have the right sequence in your head. Bank account first. FPS and Octopus immediately after. Overseas transfer service set up before your salary arrives. Documents prepared in advance so the process does not stall at the counter.
The most expensive mistakes new arrivals make are not dramatic. They are small and cumulative: monthly fees on underfunded accounts, bank exchange rates quietly eroding every international transfer, delayed payroll because HR never received your account details. None of those need to happen if you move through the setup deliberately in those first two weeks.
Hong Kong rewards the organised. Get your financial infrastructure in place early and you can spend the rest of your attention on actually settling into the city.
Read next
-
 Mobile Plans, SIM Cards and Connectivity Costs for Expats in Hong Kong
Compare 3HK, SmarTone, and CMHK mobile plans for Hong Kong expats. Monthly costs, data tiers, prepaid vs contract, and tips on staying connected abroad.
-
 Where Hong Kong Expats Actually Spend Their Evenings and Weekends
How expats in Hong Kong actually spend their free time. Hiking groups, waterfront bars, beach clubs, and the Happy Valley racing ritual with real costs.
-
 Hiring a Domestic Helper in Hong Kong: Contracts, Costs and Legal Steps
Understand Hong Kong's legal requirements for hiring a domestic helper, including the contract, minimum wage, employer levy, and lawful termination.
-
 Hong Kong Customs and Etiquette Rules Most Visitors Miss
Learn the unspoken Cantonese customs, dining taboos, and superstitions that matter in Hong Kong, from chopstick rules to gift-giving pitfalls.